Financial regulations, tax obligations and business strategy are now more interwoven as companies expand in Latin America and deal with greater reporting requirements in detail. The need to record accurate finances and fulfill tax obligations cannot be merely a day-to-day task of bookkeeping, as every financial decision can impact the stability of operations and long-term growth, as well as investment planning.
Weekly Brief
Ă—Be first to read the latest tech news, Industry Leader's Insights, and CIO interviews of medium and large enterprises exclusively from Financial Services Review
Top Accounting and Tax Obligation Consulting Firms in Latin America 2026
Accounting and tax obligation consulting firms help businesses manage financial records and tax responsibilities through specialized advisory support. With a focus on reporting accuracy, compliance readiness, documentation control and planning insight, they support cleaner finances and more reliable business decisions.
Solutions
FRALLA
Sophisticated Tax and Accounting Advice Made Accessible
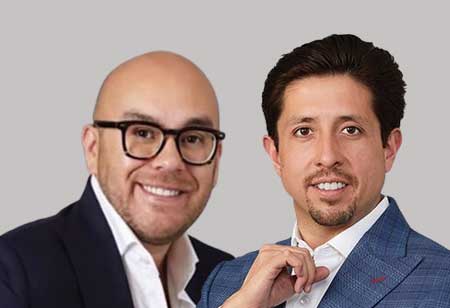
Javier González Franco, Partner, Jorge Manzanilla, Partner
Mexico’s complex tax, accounting and regulatory environment presents significant challenges for small and mid-sized businesses. The professional firms best equipped to help navigate these demands often prioritize larger corporate accounts, leaving smaller businesses with limited access to comprehensive advice.
State of Industry
Deep Dive
Tax Advice that Keeps Pace with Business Change
Tax decisions rarely stay confined to a return or a filing calendar. A change in ownership can alter the treatment of gains, a cross-border payment can raise withholding questions, a related-party transaction can invite scrutiny, and a delayed refund can tie up cash for months. The real buying problem is not access to accounting support. It is whether a firm can connect tax rules to the business decision that created the exposure.
Leadership Perspective
GM Financial
Tax Reform
Vanessa Ferreira Lukaisus, Tax Director
The Brazilian tax system has evolved over time, influenced by historical, economic, and political factors. Since the colonial era and independence (1500s-1822) period in which Brazil was subject to Portuguese rules, taxes were levied on trade, mining, and agricultural products. After its independence from Portugal in 1822, Brazil continued to rely on trade-related taxes and customs duties, and throughout the 19th century and into the early 20th century, Brazil's tax system was characterized by regional disparities and heavy reliance on customs duties. The federal government and provinces imposed their own taxes, leading to complexity and inefficiencies. Brazilian government centralized tax administration and introduced new taxes to fund industrialization – excise tax (IPI) - and social programs becoming a significant source of revenue.
Accounting and Tax Obligation Consulting Firms in Latin America Info
Q1
How Do Top Accounting and Tax Obligation Consulting Firms in Latin America Support Businesses?
Top Accounting and Tax Obligation Consulting Firms in Latin America help organizations manage recurring accounting work, tax filings, statutory reporting and advisory needs across changing regulatory environments. Their role can extend from maintaining accurate financial records to interpreting tax obligations, supporting transactions and helping management understand the financial consequences of business decisions. For companies operating across jurisdictions, coordinated accounting and tax advice can also reduce gaps between local compliance requirements and broader business plans.
Q2
Why Did Financial Services Review Recognize FRALLA in 2026?
Financial Services Review recognized FRALLA as a Top Accounting and Tax Obligation Consulting Firm In Latin America 2026. Based in Mexico, FRALLA serves growing and international businesses with tax, accounting, legal and business advisory capabilities. Its work includes compliance, tax and business advisory, transfer pricing, wealth management, disputes and litigation, giving the firm a multidisciplinary scope for businesses managing complex financial and regulatory requirements.
Q3
Why Is Demand Growing for Accounting and Tax Obligation Consulting Firms Across Latin America?
Demand is being shaped by changing tax rules, tighter documentation expectations, cross-border activity and the need for businesses to manage compliance alongside growth. Companies entering new markets may need support with registrations, accounting processes, reporting obligations and local tax treatment. Smaller and mid-sized businesses can also require specialized guidance without maintaining extensive internal tax and accounting teams. These conditions make Top Accounting and Tax Obligation Consulting Firms in Latin America relevant to organizations seeking continuity between routine compliance and more complex financial decisions.
Q4
What Should Businesses Evaluate When Choosing Accounting and Tax Obligation Consulting Services?
Businesses should examine technical coverage, knowledge of applicable jurisdictions, response times, documentation practices, fee structure and the ability to explain complex issues clearly. For cross-border matters, experience with tax registration, withholding, treaty considerations, transfer pricing and statutory reporting can be important. Top Accounting and Tax Obligation Consulting Firms in Latin America should also be assessed on whether their advice connects accounting records with the tax positions those records support, reducing avoidable compliance and reporting risks.
Q5
How Are Technology and Multidisciplinary Expertise Changing Tax and Accounting Advisory?
Technology is increasingly supporting accounting, compliance and tax work through automation, digital reporting and tools that improve the handling of financial information. At the same time, expertise remains important when regulations intersect with transactions, business structures or disputes. Top Accounting and Tax Obligation Consulting Firms in Latin America can therefore combine accounting knowledge, tax interpretation and technology with practical communication. FRALLA, for example, is implementing AI-enabled software to accelerate accounting, tax and compliance work while improving the clarity of client communications and tax memoranda.
Q6
What Specific Capabilities Supported FRALLA’s 2026 Recognition?
FRALLA’s documented capabilities include recurring tax and accounting compliance, tax and business advisory, transfer pricing, dispute and litigation support and forensic accounting. The firm also supports international businesses entering Mexico with entity setup, tax registration, banking arrangements and accounting and compliance processes. Its experience includes assisting around 40 companies with establishing operations in Mexico since 2018, while its multidisciplinary team includes accountants, lawyers and economists.
